Next available chat
See available times

Hi. I’m
Tarique.

I sell to banks, credit unions and fintechs. Full-cycle sales, business development and partnerships in Canada and the U.S.

Looking for my next full-time role.Explore my work
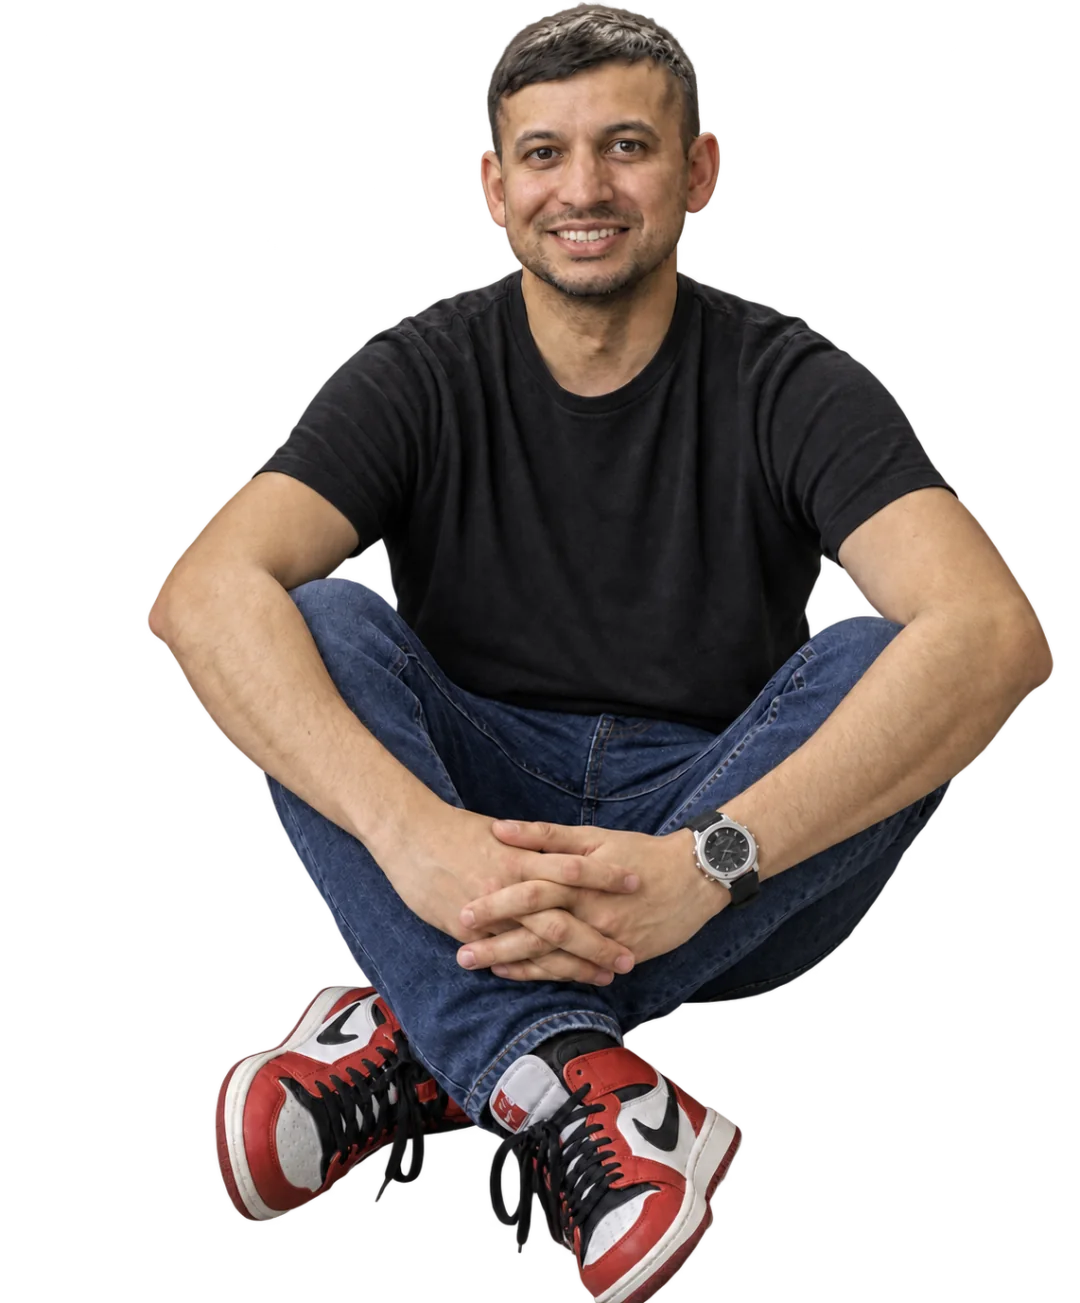
Tarique seated casually, wearing a black shirt, jeans and red trainers.

Some of the work.

Four fintech companies, from early sales hire to multi-year enterprise deals.

Where I’ve worked · most recent first

Brim Financial

Senior Director, Business Development –

Card issuing & paymentsBanks, credit unions, fintechs and brands in Canada and the U.S.

Full-cycle sales for payments infrastructure.

I built and qualified the pipeline, then ran my deals through to signature. These were multi-year enterprise deals that no one person can get signed alone, so the job was keeping people on both sides invested through the business case, proposals and RFPs, diligence and commercial terms. The contracts ran for years and grew well past their first-year value as programs launched and scaled.

Risk and diligence teams shape the decision more than the org chart suggests, so I brought the right people in early and they got direct answers.

Across the company, Brim signed or launched programs from 2022 to 2026 with Air France-KLM, Canadian Western Bank, Laurentian Bank, Affinity Credit Union and Manulife Bank.

More on the work at Brim

I opened partnership discussions where a partner already had the institution’s trust and we filled a gap for them. Direct outreach and long relationships still did most of the work.

Public bank data, product information and announcements told me which institutions had a reason to change now, and which to leave for later.

I created sales materials, including pamphlets, positioning, case studies and website content, for conversations, proposals and events.
Before Brim

RailzRailz

Director, Business Development –

Financial data & APIs

Shorter deals for a developer-first API.

5 B2B fintechs signed

I sold an accounting-data API to B2B fintechs in short-term lending and underwriting, before there was a sales playbook. Five signed on in quick-close deals, and a mid-size bank became Railz’s first U.S. bank pilot, using small-business accounting data to underwrite its SMB customers.

More from Railz

I worked backward from the credit or underwriting decision the buyer needed to make, then brought data-rights and integration questions into the conversation early.

exagensexagens

Business Development –

Behavioural bankingPersonalized guidance in digital banking

Took a new product from pivot to U.S. pilots.

2 U.S. credit union pilots

exagens pivoted into a new product class as COVID was starting, and I was there from the beginning of that pivot. Desjardins was already a marquee client, and two U.S. credit unions started pilots.

LemonadeLXPLemonadeLXP

Business Development –

Digital adoption

Built the first sales motion into banking.

At LemonadeLXP, the client base grew from one financial institution to twelve.

LemonadeLXP was a bootstrapped company moving into banking after TD asked for help with digital adoption. As one of the first business development hires, I built the first sales cycles as it expanded.

More from LemonadeLXP

New institutions had different reasons to buy, so we broadened the proposition from one use case to several.

Where I fit best.

Looking for a full-time role in sales, business development, partnerships or go-to-market.

I do my best work where the commercial side is still being built. That can be an early-stage company, or a new product or market at a larger one. I’ve sold everything from deals that close in a few months to multi-year agreements.

You’re building the commercial side.

Finding and qualifying opportunities, building a case with buyers, and getting the right people involved.

You’re expanding into Canada or the U.S.

I’ve sold into both markets and know why the buyer, timing and approach can change across the border.

Your buyer has more than one decision-maker.

Business cases, risk reviews and diligence, with everyone who has a say.

Less selling, more helping someone buy.

I start with what needs to change, whether the product fits, and who actually makes the decision.

Most of my deals started long before a proposal, through relationships and introductions.

Understand the problem first.

On knowing your market before you sell into it.

“A problem well-defined is a problem well-solved.”
Toronto Business Development Centre (opens in a new tab)

Interview published April 2026.

Read the transcript

And getting an understanding of the market is really important. And I like to say is that a problem well-defined is a problem well-solved. So for you to sit back and understand what problem you're solving and who you're solving it for, and then going and targeting those and having conversations.

The other thing I think fintechs need to be cognizant of is that the banks are also catching up. So the fintechs don't need to just compete with one another. They need to keep their eye on banks, because I think although banks are slow, once they do move, they're a behemoth, because banks aren't stupid and they're not gonna sit around and let competition take business away.

Community & curiosity.

I like knowing who’s working on what and introducing people who should know each other.

A WhatsApp group I run

Fintech North

More than 1,000 people in banking, payments and fintech. Mostly comparing notes, asking questions and making introductions.

Visit Fintech North

A project I built

Flow of Funds

Flow of Funds preview. Switching from Messages to Money changes the diagram, then a fee question focuses it on interchange. Explore a payment flow
Card-purchase preview.

Follow a card purchase beyond “approved.” See how the messages, bank settlement and merchant payout differ.

What’s on
your mind?

Say hello

Tarique Khan

I’m in Toronto. What do you want to talk about?

30 minutesBook a call Emailtarique@fintechnorth.ca ConnectLinkedIn (opens in a new tab)