Work, people, and a little curiosity.

Next available chat
See available times

Hi. I’m
Tarique.

I sell financial infrastructure, including technology for card issuing, payments and financial data, to banks, credit unions and fintechs in Canada and the U.S. Day to day, that means finding the right people, working out together whether there’s a real fit, and getting specialists from both sides into the same room when a decision needs it.

Open to commercial roles and project work.Explore my work
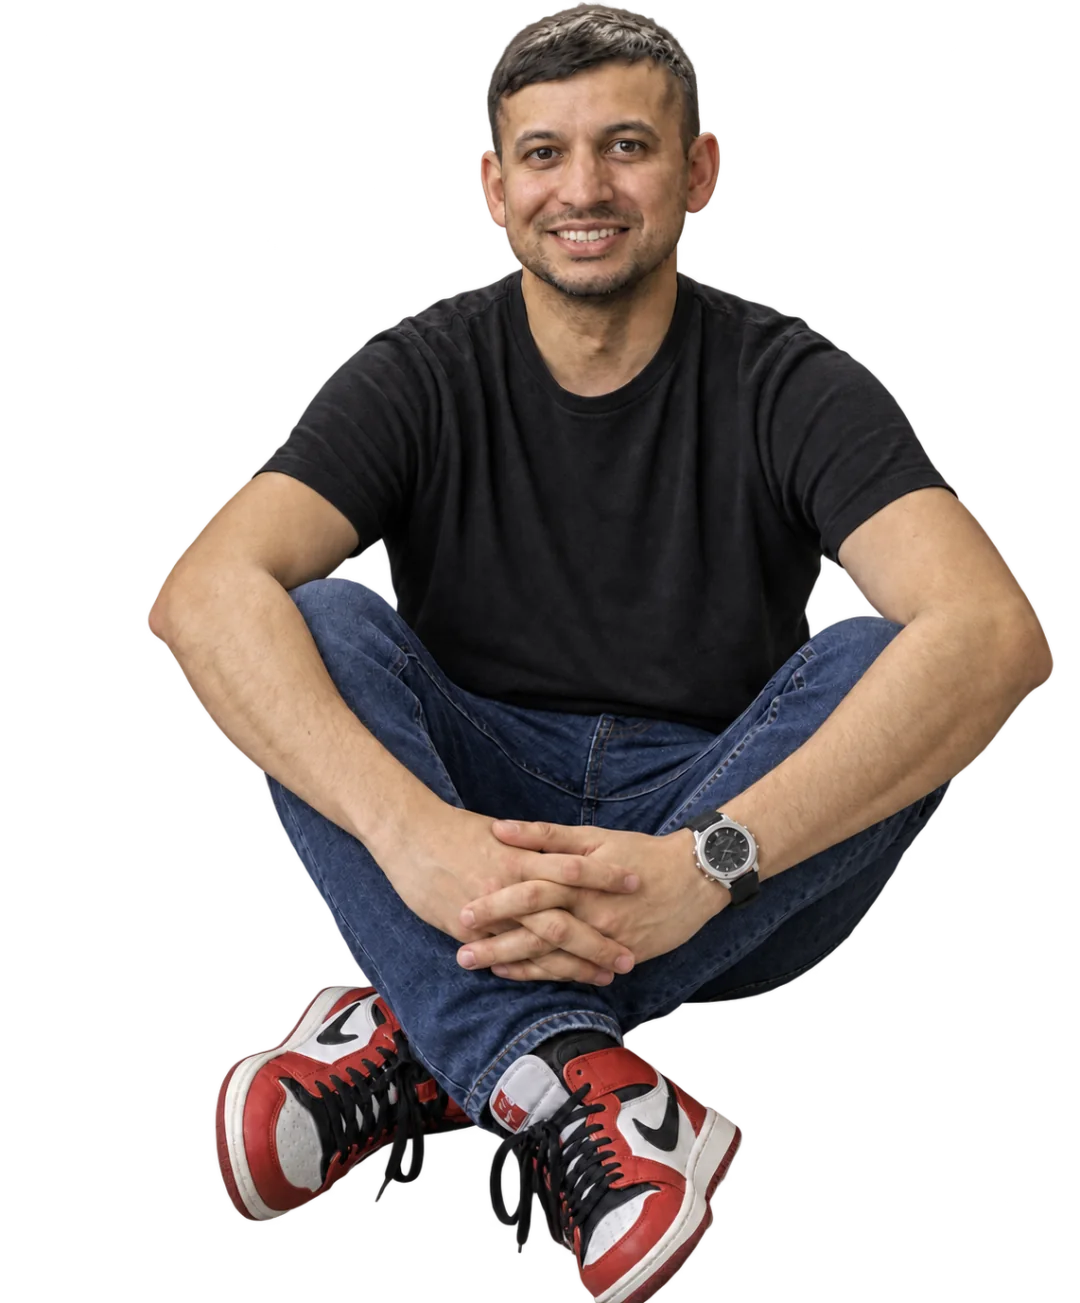
Tarique seated casually, wearing a black shirt, jeans and red trainers.

Some of the work.

Four fintech companies, selling into banks, credit unions and fintechs across Canada and the U.S. The product changes; the thread is finding the right buyers and helping them decide.

CanadaUnited States
  • Banks
  • Credit unions
  • Fintechs

Where I’ve worked · most recent first

Brim Financial

–

Card issuing & paymentsWorked with banks, credit unions and fintechs

Finding and advancing enterprise opportunities in card issuing and payments.

I owned pipeline generation for card issuing and payments infrastructure. Deciding which opportunities deserved a multi-year effort was as much of the job as finding them. I worked with buyers on the use case and business case, assembled proposals and RFP/RFI responses, and supported due diligence and commercial negotiations. My time at Brim wrapped up in September 2026.

The shape of the work

Enterprise, multi-yearagreements with long cycles and many stakeholders

Bringing the teams together.

I quarterbacked the process by bringing in the right people for technical questions, third-party risk management and due diligence. Risk and diligence teams shape the decision more than the org chart suggests, so they got direct answers early.

BrimTeams & subject matter experts
My roleBringing the
teams together.
The institutionBusiness buyer & their teams
Connecting the business case to the detail

The business team needs a case for change; specialists on both sides work through the gaps and questions.

The case for changeSpecialist inputCommercial agreement

I qualified opportunities around needs, timing, budget and decision-making authority, and said so early when the answers didn’t hold up.

A closer look at the work

I opened partnership discussions where a partner already had the institution’s trust and we filled a gap for them. Direct outreach and long relationships still did most of the work.

Public bank data, product information and announcements told me which institutions had a reason to change now, and which to leave for later.

I created sales materials, including pamphlets, positioning, case studies and website content, for conversations, proposals and events.
Before Brim

Growing a client base, adapting to a changed market, and connecting technical products to business needs.

Railz

–

Financial data & APIsLater acquired by FIS

Early sales at Railz for a developer-led data API.

Accounting-data APIBusiness case

At Railz, I sold an accounting-data API to lenders and fintechs before the product had a sales playbook. My job was turning a technical product into a credit or underwriting decision the business buyer cared about, and surfacing data-rights and integration constraints before they killed a deal.

What I took from it: start with the decision the data supports, then bring in the people who can answer the technical questions.

exagens

–

Behavioural bankingPersonalized guidance in digital banking

Reworked the proposition after COVID and opened the U.S.

2 pilotsCustomers

exagens had a product in market and Desjardins as a marquee client. COVID changed what institutions needed, so I reworked the proposition and took it to U.S. credit unions. Two pilots turned into customers.

What I took from it: a pilot needs a purpose, and the next step should follow what the institution learns.

LemonadeLXP

–

Digital adoption

Early sales hire at LemonadeLXP.

At LemonadeLXP, the client base grew from one financial institution to twelve.

I was one of the first sales hires at LemonadeLXP and grew the client base from one financial institution to twelve, mostly in the U.S., with some in Canada. The proposition went from one use case to several, because each new institution had a different reason to buy.

What I took from it: interest is not a pipeline. A credible buying reason is.

Where I fit

Where I fit best.

Open to commercial roles and project work.

Sales, business development and partnerships, with the positioning and go-to-market work around them. Also happy to talk about advisory work, a panel or podcast, or fintech in Toronto if you’re new here.

You’re building the commercial side.

Someone to find and qualify opportunities, work with buyers, and shape the positioning, proposals and materials around the sale. That’s been my job at all four companies, from early sales hire to enterprise deals.

You’re expanding into Canada or the U.S.

Banks, credit unions and fintechs buy differently on each side of the border. I’ve sold into both and can help you decide who to approach first, what matters to them and which conversations can wait.

Your product takes more than a demo to buy.

Business cases, several stakeholders, diligence and commercial terms are the normal path, not a detour. That’s the kind of sale I’ve spent the most time in, where knowing when to stop matters as much as knowing how to push.

How I work

Less selling, more helping someone buy.

I want to understand what needs to change and whether we can actually meet the need.

I work with the buyer on the business case and bring in the specialists who can answer what’s holding things up.

What can change a buying decision

The product can fit and the need can be real. Contracts, budgets, people and priorities can still change the next move.

Choose a situation to see how I approach it. These can happen in any order.

First contact

What’s in place today, what needs to change, and can we actually meet the need? I ask about timing, budget and who makes the decision, and I’d rather find a gap early than late.

Deciding what happens next

Long sales cycles cost everyone time, so a pipeline full of maybes is expensive. An opportunity needs a reason to be there and a next step someone owns, or it comes out.

What makes sense next?

  • Agree a next step

    What happens next, who owns it and when.

  • Reconnect later

    The need may be there. Agree when it makes sense to return.

  • An honest no

    If we can’t meet the need, be clear and save both sides time.

Some of that work at Brim

The conversations start long before a proposal.

Four places they tend to begin.

Relationships over yearsBanks · fintechs · the wider ecosystem

Beyond buyers, I keep in touch with people across the card networks, consulting firms, analysts and journalists. They tell me who’s working on what and where an introduction might make sense.

Staying in touchEvents · LinkedIn · industry conversations

Conferences, events, LinkedIn and the follow-ups in between, sharing what I’m seeing and asking what people are working on.

News & researchIndustry news · annual reports

Industry news and annual reports, with AI helping to find signals. Research gives me a reason for the conversation, not proof of a buying need.

Inbound & introductionsReferrals · direct enquiries · RFPs

Some come through people who know me, direct enquiries and inbound RFPs. I ask what prompted the interest; an RFP written around another vendor is a different conversation.

What I learn from buyers.

In conversation

Understand the problem first.

On knowing your market, and why fintechs need to keep an eye on banks.

Toronto Business Development Centre (opens in a new tab)

Interview published April 2026.

Read the transcript

And getting an understanding of the market is really important. And I like to say is that a problem well-defined is a problem well-solved. So for you to sit back and understand what problem you're solving and who you're solving it for, and then going and targeting those and having conversations.

The other thing I think fintechs need to be cognizant of is that the banks are also catching up. So the fintechs don't need to just compete with one another. They need to keep their eye on banks, because I think although banks are slow, once they do move, they're a behemoth, because banks aren't stupid and they're not gonna sit around and let competition take business away.

Community & curiosity.

I like knowing who’s building what, how the plumbing actually works, and which two people should probably meet. Fintech nerd, in other words. Fintech North and Flow of Funds are where that curiosity ends up.

A community I run

Fintech North

An online community of people working in banking, fintech and nearby fields. Mostly comparing notes, asking questions and making useful introductions.

How I bring people together
  • Questions
  • Shared
    experience
  • Useful
    introductions
Who has useful experience to share, and which people should meet? That’s what I listen for.
Visit Fintech North

A project I built

Flow of Funds

Flow of Funds preview. Switching from Messages to Money changes the diagram, then a fee question focuses it on interchange. Explore a payment flow
Card-purchase preview.

Follow a card purchase beyond “approved.” See how the messages, bank settlement and merchant payout differ.

Off the clock. Road cycling on my Canyon CF 7, or following an idea to see where it goes. A little more about me

What’s on
your mind?

Say hello

Tarique Khan

I’m in Toronto. What do you want to talk about?

30 minutesBook a call Emailtarique@fintechnorth.ca ConnectLinkedIn (opens in a new tab)
Save contact

Pass it along

Share this site

Meet Tarique Khan. Fintech sales & business development.

LinkedIn (opens in a new tab) WhatsApp (opens in a new tab)